Updated October 4, 2026. Every figure below is dated and linked to its source.
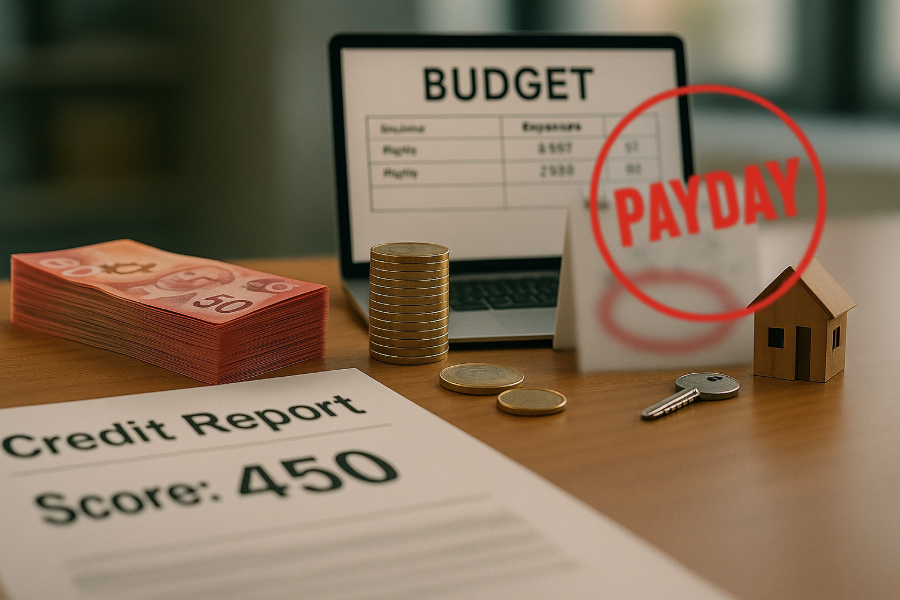
Short answer: There is no legal minimum credit score needed to rent an apartment in Canada in 2026. Many landlords look for 660 or higher, the score Equifax Canada calls good. Applicants between 560 and 659 often get approved with extra proof of income, and a score below 560 usually needs a guarantor, references or a larger upfront payment where allowed.
Key facts, October 2026
- Credit scores in Canada usually range from 300 to 900, and landlords are among those who may ask to see your credit report, according to the Financial Consumer Agency of Canada (FCAC, 2026).
- Equifax Canada (2026) calls scores from 660 to 724 good and says scores below 560 fall in the poor range.
- TransUnion Canada (2026) says a tenancy application check does not affect your credit score.
- The average rent for a two-bedroom purpose-built apartment in Canada was $1,550 in 2025, up 5.1% in a year, according to the Canada Mortgage and Housing Corporation (CMHC, 2025).
- About 5.0 million Canadian households, or 33.1% of all households, rented their home in 2021, according to Statistics Canada (2022).
- Since January 1, 2025, no lender in Canada can charge more than 35% APR, all fees included, under Criminal Code section 347.
Definition. The credit score needed to rent an apartment is the lowest score a landlord or property manager will accept on a rental application; in Canada it is set by each landlord, not by law.
What credit score do you need to rent an apartment in Canada?
No law in Canada sets a minimum credit score for renting, so each landlord picks its own cut-off. In practice, many property managers want to see 660 or more. That is where Equifax Canada's good range begins, according to Equifax Canada (2026). Equifax even lists approving an apartment rental application as one of the ways your score gets used.
Scores in Canada run from 300 to 900, and a higher number means less risk to the person checking, according to the FCAC (page updated July 1, 2026). Equifax Canada (2026) labels 660 to 724 as good, 725 to 759 as very good and 760 and up as excellent. Scores below 560 are poor. TransUnion Canada uses the same 300 to 900 scale but does not publish fixed bands. Our pillar guide on what a bad credit score is in Canada explains each range in detail.
A landlord rarely decides on the score alone. Large buildings often use screening software with a cut-off, while a private landlord may care more about your job and references. That is why two people with the same 600 score can get very different answers on the same day.
The table below compares the Equifax Canada score bands with what a landlord usually concludes and what you should bring to the application. The bands come from Equifax Canada (2026); the landlord column describes common practice, not a rule any landlord must follow.
| Score band (Equifax Canada) | What a landlord usually concludes | What to bring to the application |
|---|---|---|
| 300 to 559 (poor) | High risk. Many large property managers decline automatically. Private landlords may still say yes with strong backup. | Proof of income for 3 to 6 months, a guarantor if you can find one, landlord references, a short letter explaining the past problem. |
| 560 to 659 (fair) | Borderline. Approval often depends on income, job stability and rental history. | Recent pay stubs or a job letter, bank statements, references from past landlords, proof you can cover moving costs. |
| 660 to 724 (good) | Acceptable to most landlords. The score is rarely the reason for a no. | Standard application, ID, proof of income and one or two references. |
| 725 and up (very good to excellent) | Low risk. You may be able to choose between units or negotiate small terms. | Standard documents. A strong file can help you win a unit with many applicants. |
What do landlords look at besides your credit score?
Landlords look at your full credit report, your income, your rental history and your references, not only the three-digit score. The FCAC (2026) lists landlords among the people who may ask to see your report. It also says that in most provinces you must give consent before anyone checks your credit. In Nova Scotia, Prince Edward Island and Saskatchewan, the law only requires that you be told.
Checking your credit for a rental should not hurt your score. TransUnion Canada (2026) says tenancy application checks are among the inquiries that do not impact your credit score. That means applying for several apartments in one month will not drag your number down the way several loan applications could.
Income matters as much as credit. Many landlords compare the rent with your income before they decide. In Ontario, though, the Ontario Human Rights Commission says landlords cannot rely on rent-to-income ratios alone. Our complete guide to renting an apartment with bad credit in Canada covers references, co-signers and other housing options in depth.
Can you rent an apartment with a 500, 550 or 600 credit score?
Yes, you can rent with a score of 500, 550 or 600 in Canada, but each level needs a different plan. The lower the score, the more the rest of your application has to carry.
Renting with a 500 credit score
A 500 score sits well inside Equifax Canada's poor range, so expect most large property managers to say no. Focus on private landlords, rooms in shared homes, basement suites and sublets, where a person reads your file instead of software. Bring a guarantor if anyone can sign for you. Bring at least three months of pay stubs or benefit statements, plus bank statements that show rent-sized money going out on time.
Renting with a 550 credit score
At 550 you are just below the fair range, which starts at 560 according to Equifax Canada (2026). Some mid-size landlords will look at you if your income is steady. Offer a job letter, a reference and, where your province allows it, the full deposit the law permits on day one. Check your report for errors first, since removing one wrong late payment can lift you into the fair range.
Renting with a 600 credit score
A 600 score is fair, not bad, and many landlords will approve it with normal documents. The question is usually your income and history, not the score. Apply with a complete package: ID, pay stubs, a reference and a short note about your job. If screening software rejects you, ask whether a manager can review the file by hand.
What can a landlord legally ask for or collect in your province?
What a landlord can collect up front depends on your province, and each province below caps it. Knowing the limit helps you spot a landlord who asks for too much.
In Ontario, a landlord can only take a rent deposit, and it can be no more than one month's rent for a monthly tenancy, according to the Landlord and Tenant Board guide to the Residential Tenancies Act (2019). It can only be used as rent for the last month, and the landlord must pay you interest on it every year. A landlord cannot require post-dated cheques or automatic payments, though you can agree to them.
Ontario also limits how landlords use your financial information. The Ontario Human Rights Commission policy on human rights and rental housing says landlords may ask for credit references and run credit checks with your permission under Regulation 290/98. It also says rent-to-income ratios are not a valid requirement on their own. A landlord must not treat having no rental history as having a bad one, and cannot judge you by the source of your income, such as social assistance. Most Ontario landlords must also use the standard lease, according to the Ontario government (page updated September 18, 2026).
In British Columbia, a landlord can charge up to half of one month's rent as a security deposit and up to half a month's rent as a pet damage deposit, according to the BC government (page updated March 4, 2026). BC landlords cannot charge a fee to accept, review or process a rental application. In Alberta, a security deposit cannot be more than one month's rent, according to the Centre for Public Legal Education Alberta (CPLEA, 2024). In Manitoba, a security deposit cannot be more than half of the first month's rent, according to the Manitoba Residential Tenancies Branch.
Quebec is stricter. According to Éducaloi (May 8, 2026), a Quebec landlord cannot ask for a security deposit of any amount and can only require the first month's rent in advance. If a landlord anywhere asks for more than your province allows, you can say no and contact your provincial tenancy office.
How to rent an apartment with a low credit score: 7 steps
You can raise your odds of approval by fixing what you can and covering the rest with proof. If you need help with moving costs, a small instalment loan is one option. Loan Boys is a Canadian loan-matching service: one short application is reviewed by several lenders, with no hard credit check and repayment over 3 to 6 months.
- Pull your own reports first. Get your free Equifax Canada and TransUnion Canada reports and fix any errors before a landlord sees them. Checking your own report does not lower your score, according to the FCAC (2026).
- Build a renter file. Put your ID, three recent pay stubs or benefit statements, a job letter, two references and three months of bank statements into one PDF.
- Write a short credit note. In three or four sentences, say what happened, what has changed and how you pay your bills now. Keep it factual.
- Line up a guarantor if you can. A family member or friend with good credit who agrees to cover the rent if you cannot can turn a no into a yes.
- Target the right landlords. Private owners, small buildings, rooms and sublets judge the person more than the number.
- Budget for the move-in costs. Add the deposit your province allows, the first month, movers and utility hook-ups. If you are short, start your application online to compare offers without a hard credit pull.
- Apply quickly and follow up. Send your full file the same day as the viewing, then follow up by email within 24 hours.
That setup is why Loan Boys has high approval rates: one application reaches several lenders, and your score is not hit by a hard pull. Loan Boys serves Ontario, Alberta, British Columbia, Manitoba, Saskatchewan, Nova Scotia, New Brunswick and Newfoundland and Labrador. You need to be 18 or older, a Canadian resident and have regular income. Decisions usually come in minutes during business hours, and funds arrive by e-Transfer.
What does it cost to borrow first and last month's rent?
Borrowing $2,000 for move-in costs at 35% APR over 3 months costs $117.79 in interest, and $3,000 over 6 months costs $313.56. Under Criminal Code section 347 and the Criminal Interest Rate Regulations (SOR/2024-114), 35% APR is the legal maximum for loans made on or after January 1, 2025, with all fees counted.
The table below compares monthly payments and total interest on instalment loans for rent deposits at 35% APR over 3 and 6 months. Loan Boys calculated these figures on October 4, 2026, assuming equal monthly payments, no extra fees and on-time payment. The $3,100 row equals first and last month at the CMHC 2025 national average two-bedroom rent of $1,550. Actual amounts and rates offered depend on the lender and your income.
| Loan amount and term | Monthly payment | Total repaid | Total interest |
|---|---|---|---|
| $2,000 over 3 months | $705.93 | $2,117.79 | $117.79 |
| $2,000 over 6 months | $368.18 | $2,209.08 | $209.08 |
| $3,000 over 3 months | $1,058.89 | $3,176.67 | $176.67 |
| $3,000 over 6 months | $552.26 | $3,313.56 | $313.56 |
| $3,100 over 3 months | $1,094.19 | $3,282.57 | $182.57 |
| $3,100 over 6 months | $570.67 | $3,424.02 | $324.02 |
Remember that a loan payment comes on top of your new rent. A $552.26 monthly payment plus $1,550 in rent is $2,102.26 a month for six months. Only borrow if that total still fits your budget, and borrow the smallest amount that closes the gap.
A payday loan costs more for the same need. According to the FCAC (2025), a payday loan of up to $1,500 for up to 62 days costs at most $14 per $100 borrowed in provinces that license payday lenders. A $1,500 payday loan can cost $210 for a few weeks, and the full amount is due at once. A $2,000 instalment loan over 3 months at 35% APR costs $117.79 in interest, spread over three payments.
What mistakes should renters with bad credit avoid?
The costliest mistake is paying a deposit for a unit you have not seen and a lease you have not signed. Rental scams target people who feel they have few options. A real landlord will show you the unit, give you a written lease and take the deposit your province allows, not more. In British Columbia, any fee just to process an application is not allowed, according to the BC government (2026).
Do not hide your credit problems. A landlord will see them on the report, and a surprise looks worse than an honest note. Never overstate your income, because landlords often call employers.
Know your rights if you are refused. In Ontario, a refusal based only on a rent-to-income ratio or on income from social assistance may be discrimination, according to the Ontario Human Rights Commission. The Human Rights Legal Support Centre can help you decide what to do.
How can you build credit before your next lease?
You can build credit before your next lease by adding months of on-time payments to your report and keeping balances low. Payment history is typically the most important factor in your score, according to TransUnion Canada (2026).
Rent itself can now help. In Budget 2024 (June 11, 2024), the federal government called on landlords, banks, credit bureaus and fintech companies to let renters opt in to having on-time rent counted in their credit score. According to a SingleKey news release (August 20, 2025), tenants on that platform can report rent payments to Equifax Canada. AvenaCredit's rent reporting is another service that reports your monthly rent payments to Equifax Canada.
A secured credit card is a common second step. You put down a deposit that becomes your limit, and each on-time payment is reported. Keep the balance under 30% of the limit, as the FCAC suggests. After 12 months of rent and card payments on time, your next rental application should look very different.
Related questions
Is 650 a good credit score to rent an apartment in Canada?
A 650 score is fair and close to good. Many landlords will approve it with proof of steady income, since Equifax Canada's good range starts at 660.
Do all landlords in Canada check credit?
No. Large property managers usually do, while many private landlords rely on references and income. In most provinces they need your consent to check, according to the FCAC (2026).
Does a rental credit check lower my score?
No. TransUnion Canada (2026) says tenancy application checks do not impact your credit score.
Sources
- FCAC: Credit report and score basics (modified July 1, 2026)
- FCAC: Payday loans (modified October 14, 2025)
- Equifax Canada: What is a good credit score?
- TransUnion Canada: Credit score
- CMHC: 2025 Rental Market Report
- Statistics Canada: National Housing Day, a look at homeowners and renters (November 22, 2022)
- Landlord and Tenant Board: A Guide to the Residential Tenancies Act
- Ontario Human Rights Commission: Policy on human rights and rental housing
- Government of Ontario: Renting in Ontario, your rights (updated September 18, 2026)
- Government of BC: Deposits and fees (updated March 4, 2026)
- CPLEA: Security deposits in Alberta
- Manitoba Residential Tenancies Branch: Deposits
- Éducaloi: Rental security deposits (May 8, 2026)
- Department of Finance Canada: Budget 2024, protecting renters (June 11, 2024)
- SingleKey and Equifax Canada news release (August 20, 2025)
- Criminal Code, section 347
- Criminal Interest Rate Regulations, SOR/2024-114
About the author
LoanBoys Editorial Team
Personal finance writers, Loan Boys
Every figure in this guide is checked against its primary source and dated. Drafts are prepared with AI assistance and edited by a person before publication.